- Bitcoin
- Regulations
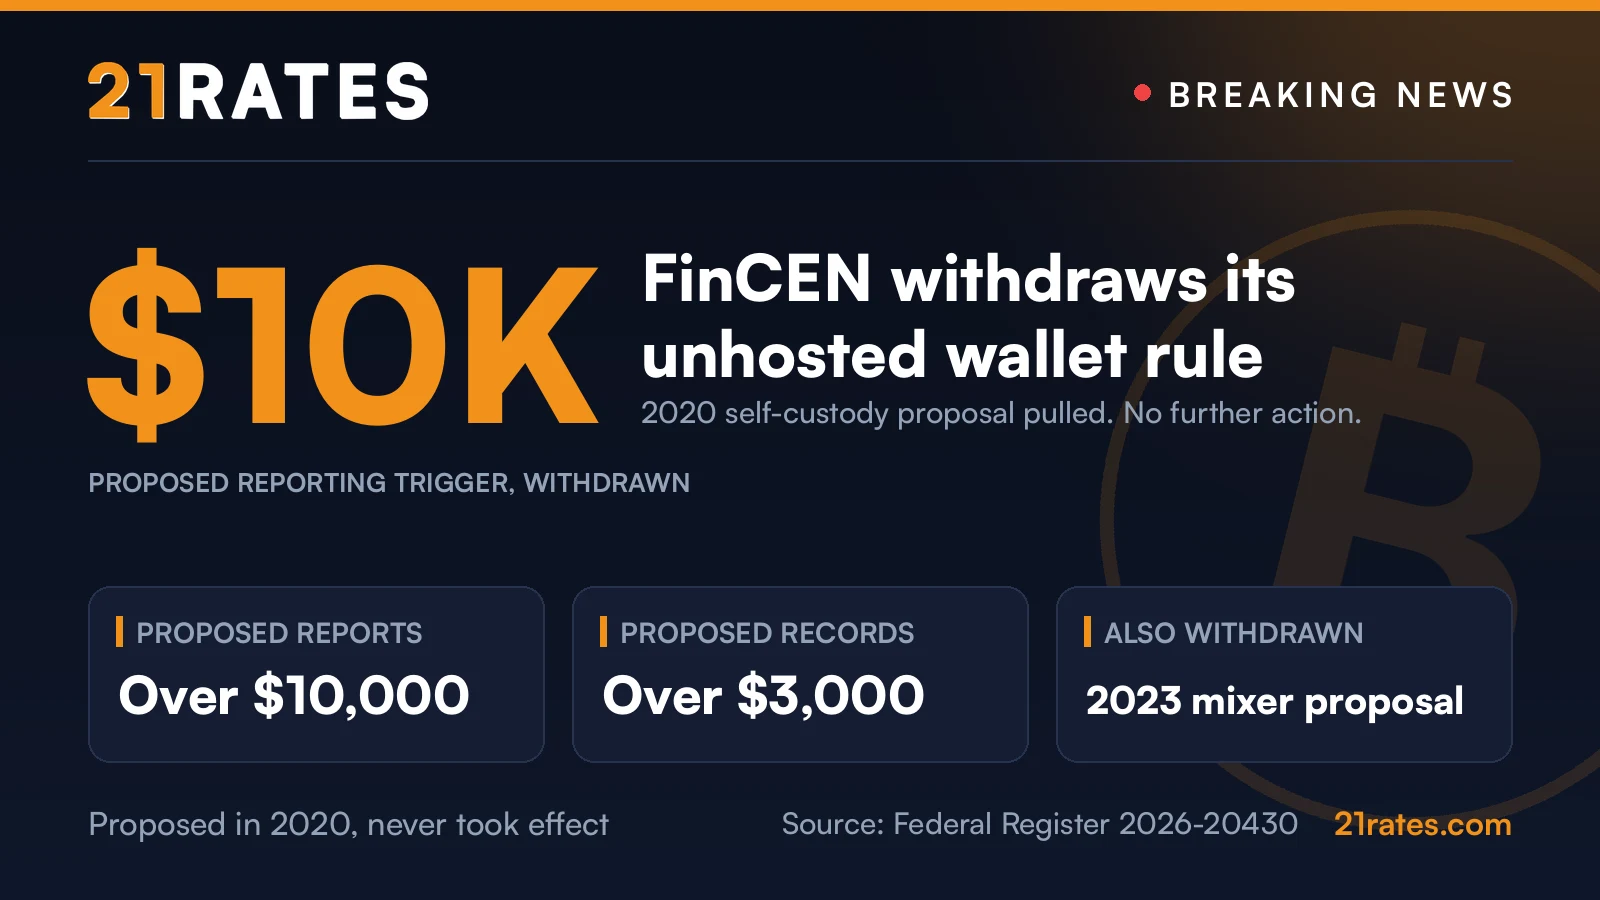
The Treasury Department's Financial Crimes Enforcement Network (FinCEN) on Monday, October 5, 2026 withdrew its December 2020 proposal that would have required banks and money services businesses to file reports on cryptocurrency transactions above $10,000 involving unhosted, or self-custody, wallets. In a withdrawal notice filed with the Federal Register and scheduled for publication on October 6, FinCEN said it "will not take any further action" on the proposal. It also withdrew a separate 2023 proposal aimed at crypto mixing.
What FinCEN withdrew
The 2020 proposal, "Requirements for Certain Transactions Involving Convertible Virtual Currency or Digital Assets," was published on December 23, 2020. It covered deposits, withdrawals, exchanges and other transfers of crypto by, through or to a bank or money services business that involved an unhosted or "otherwise covered" wallet.
The proposal described an unhosted wallet as one where "a financial institution is not required to conduct transactions from the wallet." Otherwise covered wallets were those held at a financial institution not subject to the Bank Secrecy Act and located in a foreign jurisdiction identified by FinCEN.
The proposal never took effect. The withdrawal applies as of its publication in the Federal Register.
The numbers
Under the 2020 proposal, banks and money services businesses would have had to:
- File a report with FinCEN and verify their customer's identity when a counterparty used an unhosted or otherwise covered wallet and the transaction was greater than $10,000, or when multiple transactions added up to more than $10,000 within 24 hours.
- Keep records of the transaction and counterparty, including verifying the customer's identity, for transactions greater than $3,000.
FinCEN said it is withdrawing the proposal as part of efforts to ensure digital asset regulations are "fit-for-purpose," citing the July 2025 report of the President's Working Group on Digital Asset Markets.
The mixer proposal, and the door left open
In a second notice, FinCEN withdrew its October 2023 finding, made under section 311 of the USA PATRIOT Act, that international crypto mixing is a class of transactions of primary money laundering concern. That proposal would have required covered financial institutions to report details such as amounts, wallet addresses, transaction hashes and IP addresses when they suspected a transaction involved mixing outside the United States.
FinCEN said the withdrawal was informed by commenters' concerns that the proposal's "expansive definition" of mixing could chill legitimate activity and place a large reporting burden on financial institutions.
It did not close the subject entirely. FinCEN said it "will continue to monitor activity involving CVC mixers" for signs of money laundering, terrorist financing or other illicit finance, and "may take appropriate steps in the future." Unlike the wallet notice, the mixer notice does not say FinCEN will take no further action.
Why it matters for bitcoin holders and borrowers
Moving bitcoin between an exchange or lender and a wallet you control is routine for long-term holders. Taking coins off a platform, sending collateral to a lender, or getting it back after a loan is repaid can all involve a regulated business on one side and a self-custody wallet on the other.
The 2020 proposal would have added a reporting and identity layer to those transfers above the stated thresholds. With it withdrawn, that specific requirement is off the table. The withdrawal removes a proposal; it does not change rules that are already in force.
For borrowers, custody remains one of the most important terms to check: who holds the collateral during the loan, and where it goes when the loan is repaid. 21rates.com compares bitcoin lending and borrowing rates alongside custody models across lenders.
What to watch
- Publication. Both withdrawals take effect when they appear in the Federal Register, scheduled for October 6.
- Mixers. FinCEN kept the option to act again on mixing if it sees illicit activity.
- Other agencies. The notices landed the same day the CFTC opened comment on federal rules for leveraged crypto trading, which also turn on where coins are held.
Bitcoin traded near $85,674 at 3:38 PM ET on Monday, according to Yahoo Finance data, after holding above $85,000 earlier in the day, as Benzinga reported.
More Articles About Bitcoin
Bitcoin Custody Minimum Balance: A Practical Shortlist
The dated 21Rates directory lists some custody minimums as None, while explicit thresholds start at $50,000. These are directory listings as of Nov 5,...
November 20, 2026
Why Is Bitcoin Down? A Hawkish Fed and $2.9B in ETF Outflows Push BTC to a Four-Month Low
Bitcoin fell to a four-month low as Fed officials discussed rate hikes and US spot Bitcoin ETFs recorded about $2.9 billion in November outflows....
November 19, 2026
Bitcoin Exchange Identity Verification: Check Before Funding
Bitcoin exchange identity verification, residence eligibility and funding currency are separate checks. The 21Rates River and Kraken profiles inspecte...
November 19, 2026
Podcast Conversations About Bitcoin

Buying Bitcoin Isn’t Enough | The Bitcoin Advice Nobody Talks About
Buying Bitcoin may be the beginning — but it shouldn't be the end. This conversation challenges the ...

Bitcoin's Biggest Obstacle Isn't What You Think | Ophelia Snyder
In this episode of The Daily Stack, we sit down with Ophelia Snyder, co-founder of 21Shares, the com...

Bitcoin Is Changing — Self-Custody, Saylor & the New Bitcoin Era
Bitcoin is changing — and the biggest debate may not be about price. In this episode, we dive into t...